Way 1: small business
The tenant is a small business under § 19 - switch it on, and the next run books it.
With the small-business switch on, every tax-free sale books to the § 19 account - whether it stays in Germany, goes into the EU or outside it. Without VAT and without a tax key; the handout notes it for the tax firm.
| Purpose | SKR03 | SKR04 | Tax |
|---|---|---|---|
| Tax-free revenue § 19 UStG | 8192 | 4184 | § 19 UStG, without a key |
8192 and 4184 are the accounts of the charts from 2025; your tax firm enters a different account on the tenant.
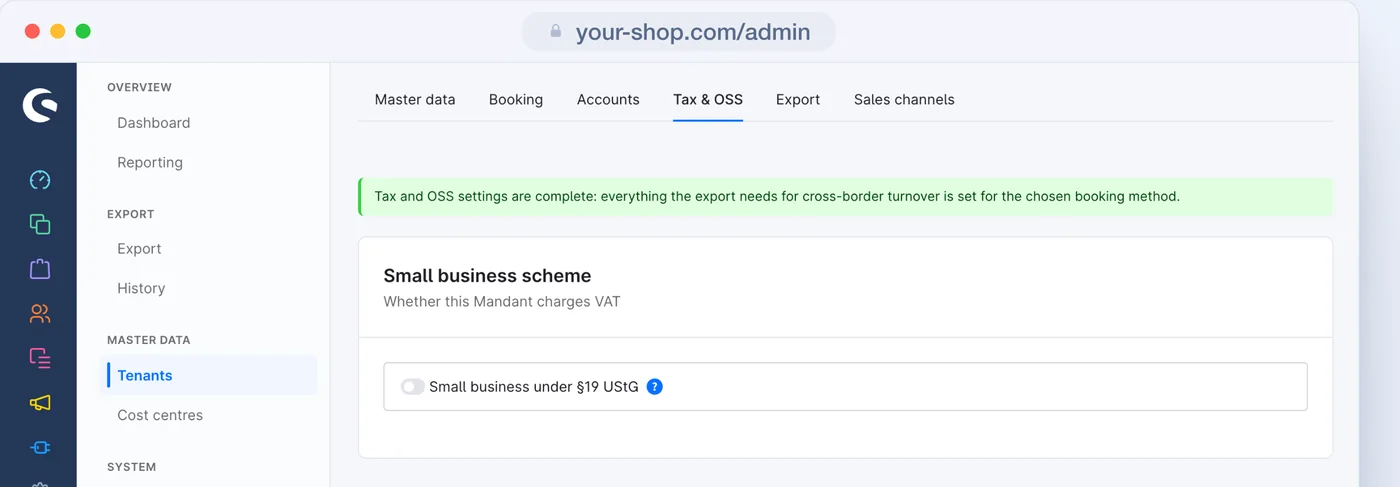
A tax-free domestic sale can mean many things: a small business, another exemption or a mistake in the tax rules. Without the switch the document stops, the run writes no file, and "What to do" shows both ways.
The tenant is a small business under § 19 - switch it on, and the next run books it.
An exemption under § 4 or a mistake - then clear it up with the tax firm and correct the taxation of the order.
The export does not resolve such contradictions silently but names them.
If a document under § 19 shows VAT, it stops instead of letting the tax disappear silently in the tax-free amount.
Everything books to the § 19 account - right below the delivery threshold, not above it. The run names the combination.
Revenue accounts per tax rate stay unused under § 19. The readiness check says so before anyone looks for them.
Up to €10,000 EU-wide a year, § 19 also covers your sales to private customers in other EU countries. The monitoring counts them, buyers with a VAT ID excepted, and warns before the limit on the tenant, on the dashboard and on the export page. Once it is crossed, the export reports it as a finding; clear up the way forward with your tax firm - registering in the destination country or the procedure under § 19a UStG.
Only the bookings: all tax-free sales book to the § 19 account without VAT and without a tax key. The format, the header and the documents stay the same.
An account per destination country or a collective account with a tax key; plus the delivery threshold.
Booked on the real payment date, with payments and refunds; OSS and EU business customers on the invoice date.
Intra-community supply and reverse charge to companies with a VAT ID.
Tax-free export, taxed deliveries outside the EU and the special case of Northern Ireland.
General reversal or side switch, credit note, cancellation and the real refund.
Amount in the document currency, rate and base amount in euros.